
Debt Payoff Planner & Tracker
- Rating
- 4.5
- Downloads
- 500.00K
- Content Rating
- Everyone
Debt Payoff Planner & Tracker - Screenshots
Pros
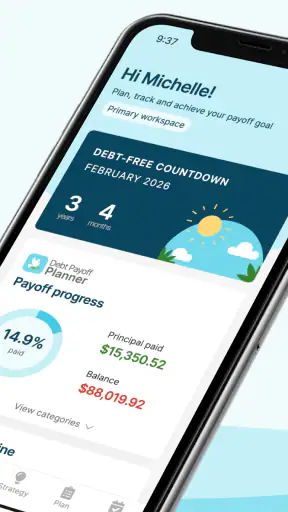
- Creates a clear payoff timeline for multiple debts.
- Supports popular repayment strategies
- including snowball and avalanche.
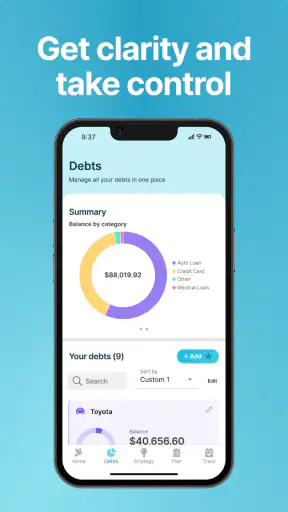
- Lets you track balances and progress toward becoming debt-free.
- Visual projections make interest costs easier to understand.
- Useful reminders can help maintain consistent payment habits.
Cons
- Advanced planning tools may require a paid subscription.
- Results depend on entering accurate balances and interest rates.
- Does not make payments or connect with every lender.
- Some users may find debt setup time-consuming.
- Frequent notifications could feel overwhelming for some users.
Debt Payoff Planner & Tracker - Description
- App Name
- Debt Payoff Planner & Tracker
- Package Name
- com.oxbowsoft.debtplanner
- Developer
- Easily get a plan and stick to it - OxbowSoft LLC
- Category
- Finance
- Last Updated
- Jan 8, 2015
- Version
- 2.54
Debt payoff is rarely difficult because people do not understand that owing money costs them. The difficult part is turning several balances, interest charges, minimum payments, and changing due dates into a plan that feels manageable. I found Debt Payoff Planner & Tracker most useful in that exact space. It is a focused finance app from Easily get a plan and stick to it - OxbowSoft LLC, built around organizing debt, watching progress, and keeping motivation visible instead of leaving everything scattered across statements and notes.
My overall impression is that it works best as a personal planning companion, not as a bank replacement or a complete household budgeting system. That distinction matters. If your immediate problem is “I need to see how my debts fit together and choose a payoff order,” this app has a clear purpose. If you need automatic account synchronization, investment tracking, bill negotiation, or a full financial dashboard, you may find its scope too narrow.
What the app is really trying to solve
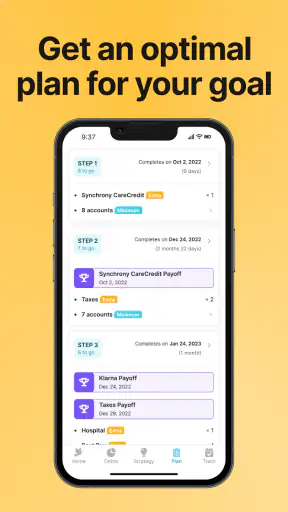
The short description calls it a debt payoff planner, but in daily use I see it as a decision-making tool. It gives you a place to turn a vague goal such as “get out of debt” into a sequence of balances and payments. That change in perspective is important: a balance is discouraging when it is viewed alone, but a planned series of payments gives you something concrete to revisit.
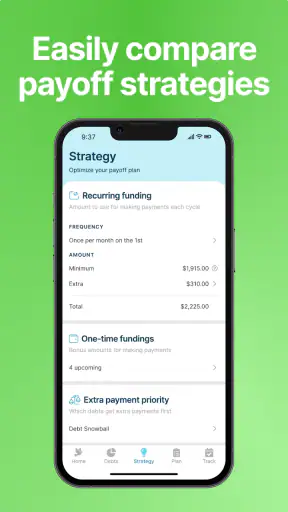
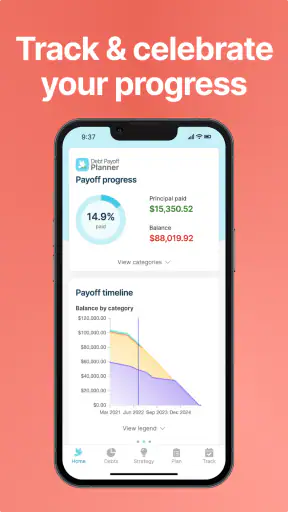
The app’s store summary presents the experience as planning, tracking, and celebrating. I would describe the same flow more practically: you establish your debt picture, follow the chosen strategy, then use visible progress to stay engaged. The motivational side is not a substitute for income or discipline, but it can help with the emotional fatigue that comes from making the same payment decisions month after month.
I tested it with the mindset of someone who has more than one obligation and wants a repeatable routine. The useful question is not simply whether the app can display a debt. Almost any notes app can do that. The useful question is whether opening it helps you decide what to pay next, understand the effect of an extra payment, and keep your plan aligned with reality.
Setting up a plan without losing the bigger picture
A good first session should be treated as an inventory exercise rather than a race to start paying. Gather current statements before entering anything, including the balance, minimum payment, interest information, and due-date details that matter to your own plan. Entering rounded guesses may make the screen look cleaner, but it can lead to a payoff projection that feels precise while being based on weak inputs.
One of my practical recommendations is to separate “known today” from “needs checking.” If an account statement is old, verify it before making the app’s schedule your household rule. The planner is only as useful as the figures you maintain. This is a common limitation of manual debt tools: they can organize your information, but they cannot rescue a plan built from forgotten fees, changed rates, or an account that was recently transferred.
Once the debts are represented, the app becomes more valuable as a regular checkpoint. I would not open it only when feeling guilty about spending. A calmer routine works better: review after statements arrive, update balances after payments clear, and then look at whether your next planned payment still fits your cash flow.
Choosing a payoff approach thoughtfully
Debt payoff methods often involve a trade-off between mathematical efficiency and emotional momentum. A strategy that prioritizes the most expensive debt can reduce interest over time, while a strategy that targets a smaller balance first may create an earlier sense of completion. Debt Payoff Planner & Tracker is most helpful when you use it to make that trade-off visible rather than blindly following whichever order feels familiar.
For me, the important insight is that the “best” order depends on what you can keep doing. If a mathematically attractive plan leaves no room for ordinary expenses, it is not a strong plan. I would rather choose a slightly less aggressive payment that survives an awkward month than set an impressive target that forces me to use a card again.
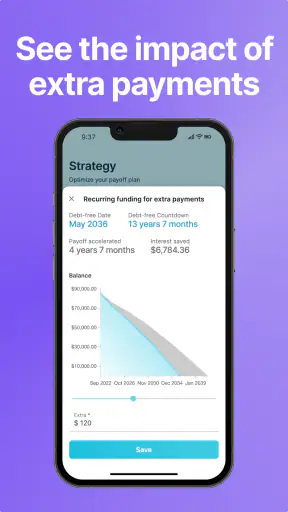
Another useful workflow is to create a baseline payment plan before experimenting with extra money. Start with what you can reliably pay, then consider how a tax refund, overtime, gift, or cancelled subscription might change the timeline. Treat irregular income as optional acceleration, not as a permanent part of the plan. That protects the core routine when the extra money does not appear.
Tracking progress without mistaking estimates for promises
Progress tracking can be motivating, but it needs interpretation. A projected payoff path is a planning aid, not a guarantee that every lender will calculate interest in exactly the same way or that no fee will appear. I would use the app to answer questions such as “Which balance should receive my next extra payment?” and “How much progress did this payment create?” I would still use lender statements as the authority for the actual balance and payment status.
This distinction is especially important when payments post on different dates. A payment may leave your bank account before a lender applies it, and a displayed balance may not update at the moment you expect. If the app and a statement disagree, I would correct the plan using the statement rather than assuming the app is wrong in every respect or that the lender is wrong.
The strongest habit is to record changes consistently. Updating only the most visible account can make the overall picture misleading. A small balance that is nearly finished may attract attention, while an account with a changing rate or fee quietly becomes more expensive. A complete review keeps the motivational view connected to the financial reality.
A realistic monthly routine
Imagine a household with a personal loan, a credit card, and a store balance. Payday arrives, the minimum payments are covered, and there is a modest amount left for an extra payment. Instead of dividing that money randomly, I would open the planner, review the chosen order, confirm that the minimums have already been accounted for, and direct the extra amount to the intended target. After the payment clears, I would update the relevant balance and check whether the next month’s plan still makes sense.
The benefit is not just arithmetic. That routine creates a pause between having spare money and spending it automatically. It also makes progress easier to discuss with a partner because the conversation can be about a shared sequence rather than an argument based on memory. I would still keep a separate emergency buffer; sending every available dollar to debt can create a fragile plan if a repair or medical expense arrives.
Where trust depends on your own review
Because this is a finance app, I pay attention to control and transparency more than I would with a casual utility. The public product information identifies the developer as Easily get a plan and stick to it - OxbowSoft LLC and places the app in the Everyone age category. It has a 4.5 average from around 4.7 thousand ratings, with around 1.2 thousand written reviews, and it has passed the half-million-install mark. Those details suggest that it is an established consumer tool, but popularity alone is not proof that it is suitable for handling every sensitive financial detail.
I would therefore begin with the minimum information needed to build a useful plan. Avoid placing full card numbers, security codes, online-banking passwords, or unnecessary personal identifiers into notes or debt labels. Use recognizable names such as “main card” or “education loan” rather than details that would make the record more sensitive if someone else saw your phone.
The app’s trust question is not only about the developer. It is also about your habits. Review the permissions shown by your device when installing or updating, and pay attention to any account, backup, export, notification, or sharing choices presented inside the app. I do not treat a finance label as permission to assume that every possible protection exists. I look for visible controls and make deliberate choices instead of accepting prompts automatically.
Account access, privacy, and moments that deserve caution
Personal debt information can reveal more than a balance. It may show where you shop, whether money is tight, which obligations are shared, or when a payment is due. That means I would be careful when using the app on a shared tablet, a work phone, or a device that other people can unlock. Notifications can also expose sensitive context, so I would review notification settings and keep previews limited if privacy matters in your household.
I would also pause before entering a debt while connected to an unfamiliar device or handing the phone to someone for troubleshooting. This is not a criticism unique to this app; it is a sensible boundary for any tool containing financial information. The key point is that a planner should reduce financial stress, not create a new privacy risk through casual handling.
When an app offers optional account creation, synchronization, backup, or sharing, I prefer to decide based on the benefit I receive. A convenience feature may be worthwhile if it prevents lost work, but it also deserves a look at the screen explaining what is being stored and where. If a feature is not necessary for my workflow, I leave it off. That is a more reliable approach than assuming that every convenience is harmless or that every data request is excessive.
How much control does the user retain?
The app’s greatest value is that it encourages the user to make the plan explicit. You decide what debts belong in the picture, how much you can realistically contribute, and whether an extra payment is sustainable. That makes it more useful than a passive balance display. It can show the consequences of a decision, but it cannot decide whether your rent, food, insurance, or emergency savings should come first.
I would use this control to test scenarios conservatively. For example, compare a normal month with a month where an extra payment is unavailable. If the plan collapses immediately, the target is too aggressive. Then test a smaller recurring amount and reserve occasional windfalls for acceleration. This approach turns the tracker into a stress test rather than a source of pressure.
There is also value in keeping the plan honest when circumstances change. A reduced work schedule, a new household expense, or a rate change should trigger an update. Do not keep following an old target simply because the original projection looked encouraging. A revised plan is not failure; it is a more accurate description of your current situation.
What it does better than familiar alternatives
Compared with a paper worksheet, Debt Payoff Planner & Tracker is easier to revisit and more engaging for someone who needs progress to remain visible. A spreadsheet offers greater freedom and can combine debt with a full household budget, but it also requires more setup, more formulas, and more willingness to maintain the structure. I would choose the app when the main task is debt order and momentum, and a spreadsheet when I need custom categories, detailed cash-flow forecasting, or a shared financial model.
Compared with a general budgeting app, this tool keeps attention on repayment rather than dividing it among groceries, subscriptions, savings, investments, and spending categories. That narrow focus is a strength for a person who already has a workable budget and wants a dedicated payoff view. It is a weakness for someone whose debt problem is mainly caused by not knowing where their monthly money goes.
Compared with a lender’s own portal, it can provide a broader picture across multiple creditors. The lender remains better for official balances, transaction history, payment confirmation, and account-specific notices. I would use both: the lender for truth at the account level, and the planner for the personal strategy across accounts.
Cost, platform age, and practical expectations
The app is free to install, with optional in-app purchases ranging from $6.99 to $41.99 per item. I would start with the free experience and decide whether any paid option solves a problem I actually have. Do not pay merely because a premium prompt appears during an emotional moment after looking at your total debt. First establish whether the basic planning routine is useful and whether the additional control is relevant to your needs.
It was released on January 8, 2015, and the current version is 2.54. It supports devices running Android 6.0 or later. That makes compatibility fairly broad for many Android users, though I would still check how it behaves on an older phone before relying on it as the only place where a plan is recorded. Keeping a private backup of important figures is sensible, especially during a device change or major app update.
The Everyone rating makes it approachable for a wide audience, but age suitability should not be confused with financial suitability. A younger user may still need help understanding interest, minimum payments, and the consequences of missing a due date. The app can organize a plan; it should not be treated as financial advice or as a replacement for speaking with a qualified adviser when debt has become unmanageable.
Who should use it, and who should look elsewhere?
I would recommend it to someone with several debts who wants one dedicated place to compare balances, maintain a payoff order, and see progress over time. It is also a good fit for people who become discouraged by slow results and benefit from a visible sequence of smaller milestones. Couples may find it useful as a shared discussion aid, provided they agree on what information to enter and protect access to the device.
I would be more cautious about recommending it to someone who needs automatic synchronization, detailed spending analysis, or a complete plan covering debt, savings, taxes, and investments. A person with unstable income may also need a broader cash-flow tool before committing to an aggressive payoff schedule. If debt involves collection activity, legal notices, or payments that are already impossible to meet, a tracker alone is not enough; professional guidance and direct communication with creditors may matter more.
It is also not the right choice if you know you will avoid manual updates. An outdated planner can be worse than no planner because it creates false confidence. In that case, a tool that connects more closely to your existing financial routine may be worth considering, even if it provides less focused motivation.
My cautious verdict
The best way to use this app is as a clear decision layer between official lender statements and your everyday payment routine. I like its focused purpose and the way it can make an intimidating collection of debts feel like a sequence of manageable decisions. Its motivational element is useful when it leads to consistent action, not when it encourages unrealistic payments.
My trust in the experience would come from using it deliberately: enter only what is needed, review device and in-app choices, protect the phone, verify figures against statements, and keep a backup of the plan. Those habits matter because a debt planner handles information that deserves care, even when the app itself feels simple.
After using it, I would describe Debt Payoff Planner & Tracker as a practical, specialized companion rather than an all-purpose financial command center. It is free to begin, has a 4.5 average from around 4.7 thousand ratings, and comes from a developer with a product identity centered on making a plan and sticking to it. If that is the specific problem you want to solve, it is worth trying. If your real need is full budgeting, automated account data, or urgent debt intervention, choose a broader or more specialized solution instead.
For my own routine, I would keep the app open during the monthly review, use lender statements to verify every important change, and treat the payoff projection as a guide rather than a promise. Used that way, it can provide something genuinely valuable: not a magic escape from debt, but a calmer method for deciding what to do next.
FAQ
What is Debt Payoff Planner & Tracker used for?
Debt Payoff Planner & Tracker is designed to help you organize debts and create a clearer repayment strategy. You can record balances, interest rates, minimum payments, and due dates, then compare payoff approaches such as the debt snowball or debt avalanche. The app is primarily a planning and tracking tool, so it does not pay creditors or manage your accounts automatically.
How does the app calculate my debt payoff plan?
The app uses the information you enter, including your outstanding balance, interest rate, minimum payment, and any additional amount you can afford to pay. Based on those details, it estimates repayment timelines and may show how different payoff methods affect interest and completion dates. Results are only estimates, so accuracy depends on keeping your debt information and payment assumptions up to date.
Can Debt Payoff Planner & Tracker connect to my bank or credit accounts?
Whether automatic account connections are available depends on the app version, platform, region, and supported financial institutions. In many cases, users can manually enter and update their debt information instead of linking accounts. Before relying on automatic synchronization, check the app’s current permissions, supported providers, privacy policy, and update frequency to understand exactly what information is accessed and how it is protected.
Is my financial information safe when using the app?
Debt Payoff Planner & Tracker handles sensitive financial details, even if you only enter balances and payment information manually. Before adding real data, review its privacy policy, storage practices, encryption claims, backup options, and any third-party services it uses. Avoid entering bank passwords unless an official, secure connection is clearly provided, and use device security features such as a passcode or biometric lock.
Is Debt Payoff Planner & Tracker free to use?
The app may offer a free version with basic debt tracking and planning features, while advanced tools can be restricted by subscriptions, one-time purchases, or other in-app charges. Pricing and available features can change between Android and iOS. Check the relevant store listing before downloading, paying particular attention to trial periods, renewal terms, advertising, and whether your data remains accessible if you cancel.


